Start here
First-time home buyers
Every question answered, from pre-approval to keys. Swipe or use the arrows to move through it one page at a time.
Swipe sideways, use the arrows, or tap a square to jump.
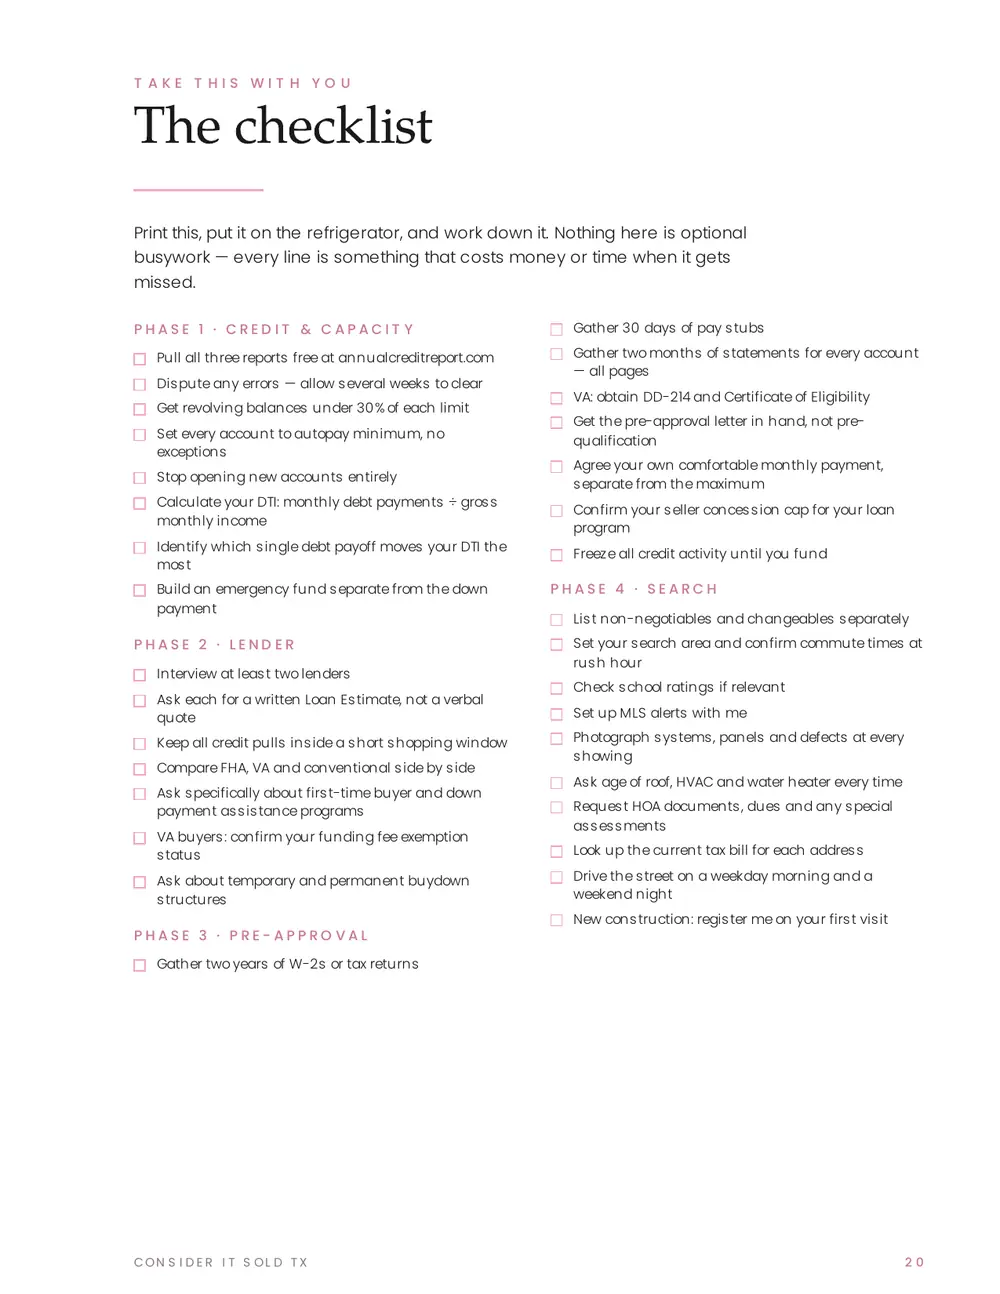
Phase 1 · Credit & capacity
Phase 2 · Lender
Phase 3 · Pre-approval
Phase 4 · Search
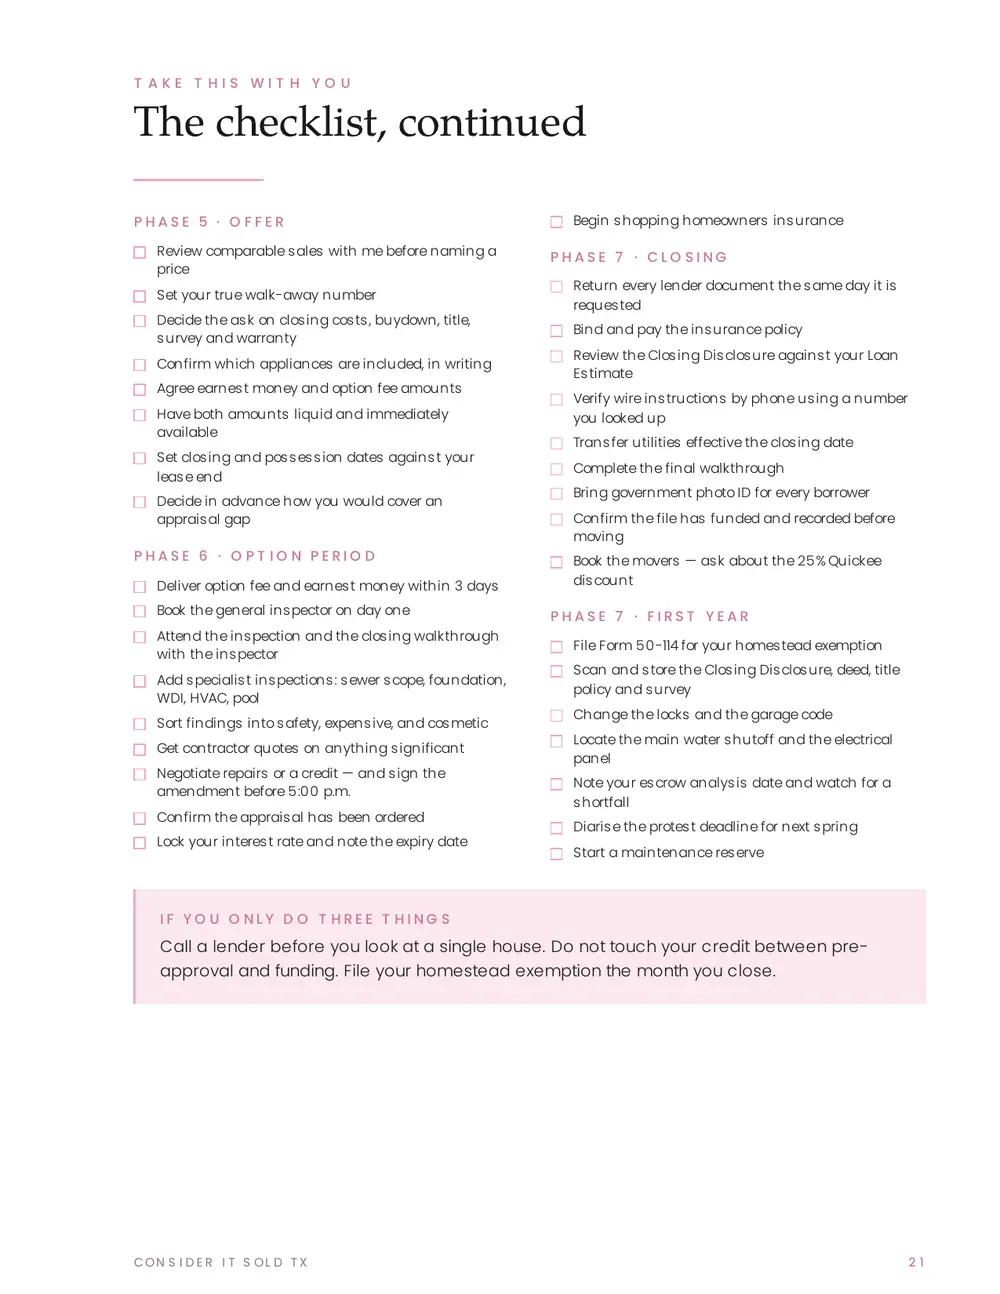
Phase 5 · Offer
Phase 6 · Option period
Phase 7 · Closing
Phase 7 · First year
Call a lender before you look at a single house. Do not touch your credit between pre-approval and funding. File your homestead exemption the month you close.
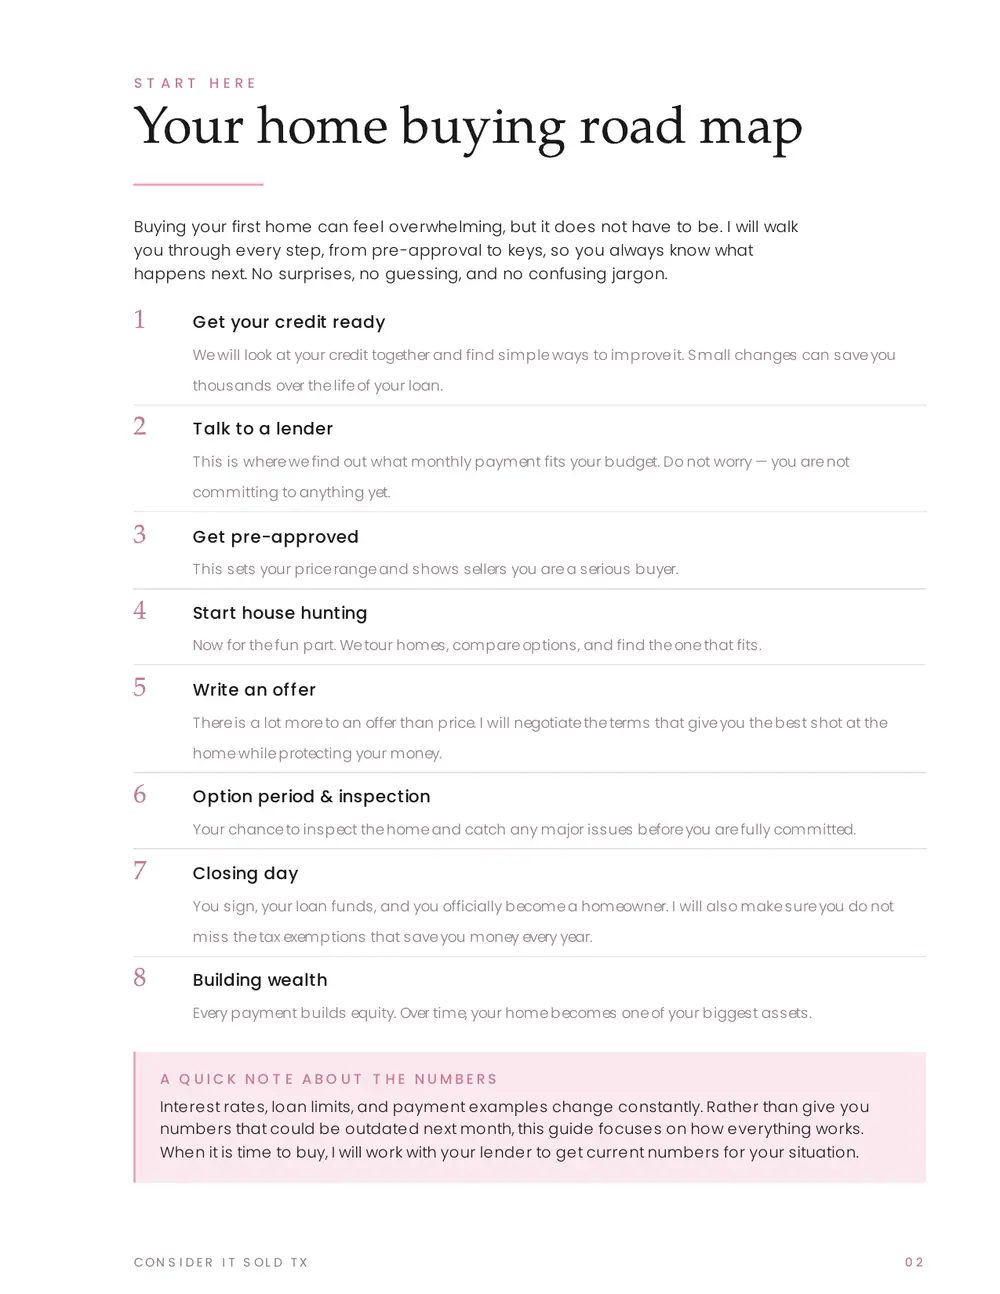
Buying your first home can feel overwhelming, but it does not have to. This guide walks you through every step in the order it actually happens, so you always know what comes next.
The printable edition
The full guide as a PDF, laid out for printing. Same content, designed for paper and for reading offline.
The checklist
Every action item from all eight phases, as a tappable list that remembers what you have already done.
Your home buying road map
- Get your credit readyWe will look at your credit together and find simple ways to improve it. Small changes can save you thousands over the life of your loan.
- Talk to a lenderThis is where we find out what monthly payment fits your budget. Do not worry, you are not committing to anything yet.
- Get pre-approvedThis sets your price range and shows sellers you are a serious buyer.
- Start house huntingNow for the fun part. We tour homes, compare options, and find the one that fits.
- Write an offerThere is a lot more to an offer than price. I will negotiate the terms that give you the best shot at the home while protecting your money.
- Option period & inspectionYour chance to inspect the home and catch any major issues before you are fully committed.
- Closing dayYou sign, your loan funds, and you officially become a homeowner. I will also make sure you do not miss the tax exemptions that save you money every year.
- Building wealthEvery payment builds equity. Over time, your home becomes one of your biggest assets.
Interest rates, loan limits, and payment examples change constantly. Rather than give you numbers that could be outdated next month, this guide focuses on how everything works. When it is time to buy, I will work with your lender to get current numbers for your situation.
Before phase 1: why buy — and when renting is smarter
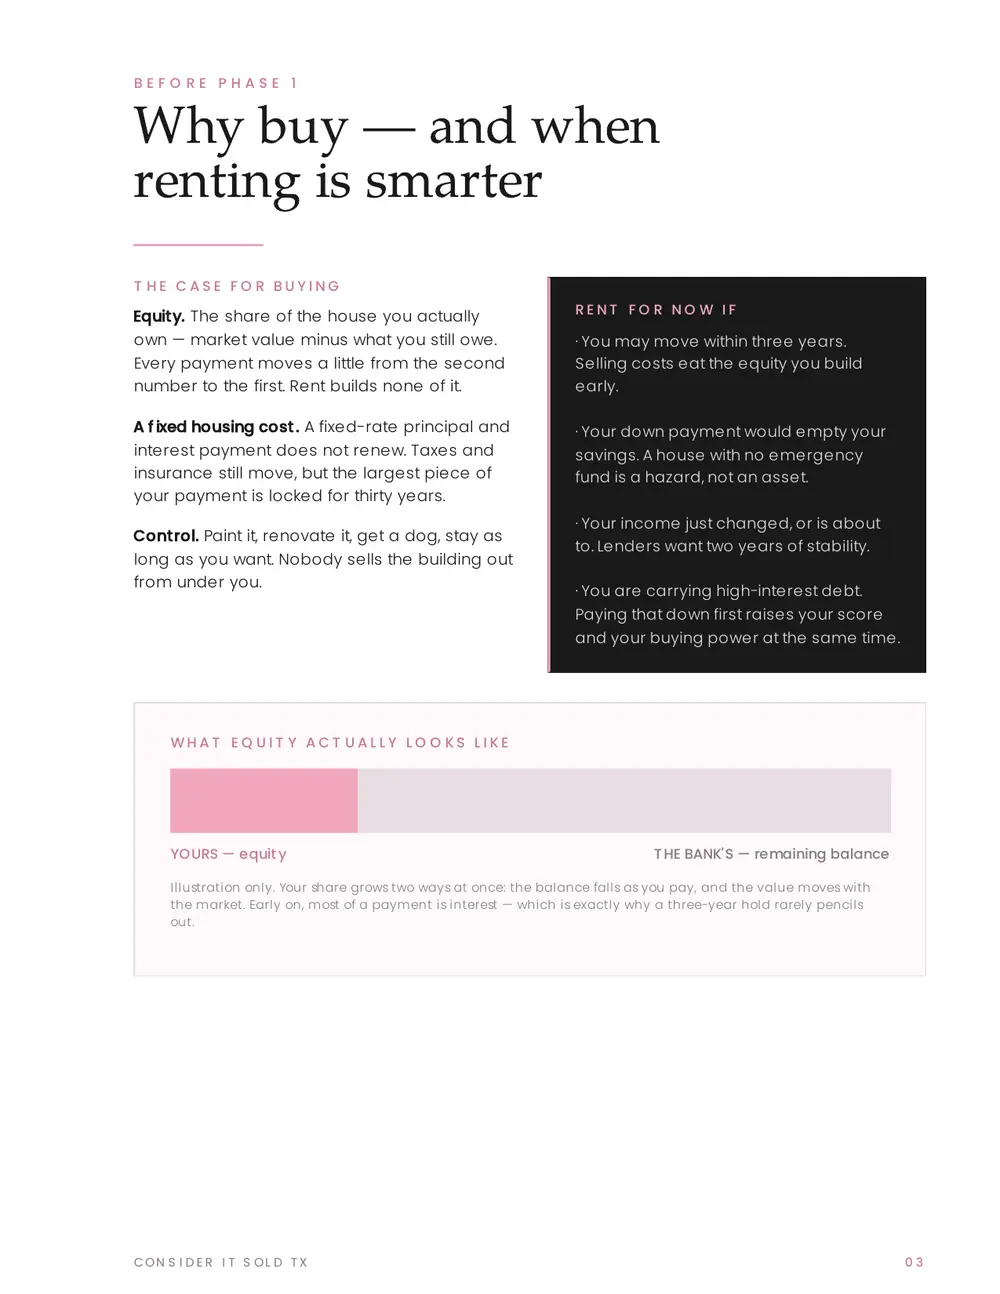
Equity. The share of the house you actually own — market value minus what you still owe. Every payment moves a little from the second number to the first. Rent builds none of it.
A fixed housing cost. A fixed-rate principal and interest payment does not renew. Taxes and insurance still move, but the largest piece of your payment is locked for thirty years.
Control. Paint it, renovate it, get a dog, stay as long as you want. Nobody sells the building out from under you.
You may move within three years. Selling costs eat the equity you build early.
Your down payment would empty your savings. A house with no emergency fund is a hazard, not an asset.
Your income just changed, or is about to. Lenders want two years of stability.
You are carrying high-interest debt. Paying that down first raises your score and your buying power at the same time.
Illustration only. Your share grows two ways at once: the balance falls as you pay, and the value moves with the market. Early on, most of a payment is interest — which is exactly why a three-year hold rarely pencils out.
Phase 1
Credit and capacity
Your score decides whether you qualify and at what rate. Your debt-to-income ratio decides how much house. Most people only think about the first one.
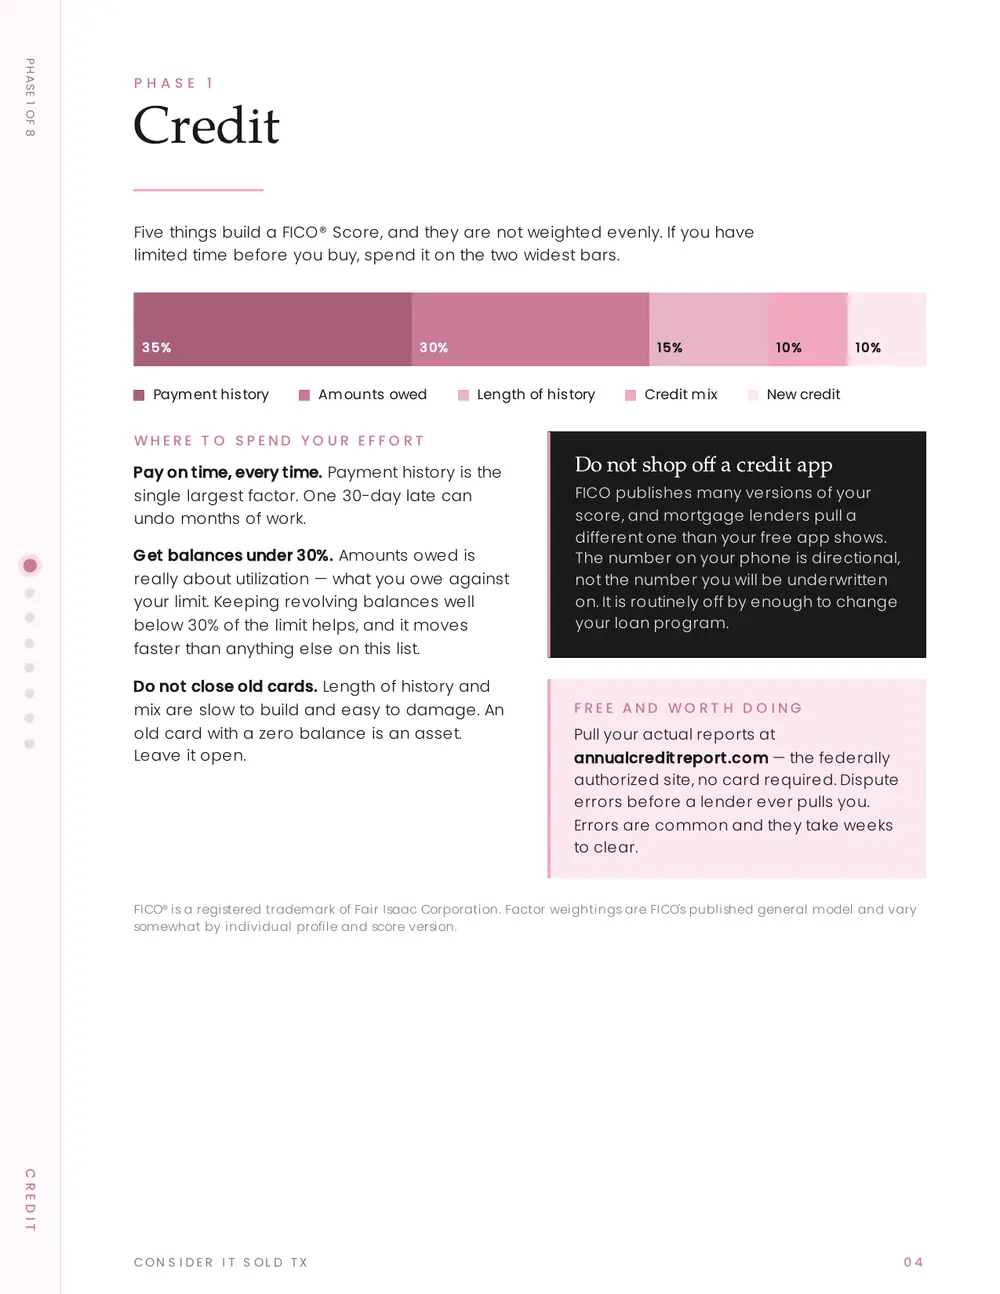
What actually builds your score
Five things build a FICO® Score, and they are not weighted evenly. If you have limited time before you buy, spend it on the two widest bars.
Where to spend your effort
Pay on time, every time. Payment history is the single largest factor. One 30-day late can undo months of work.
Get balances under 30%. Amounts owed is really about utilization — what you owe against your limit. Keeping revolving balances well below 30% of the limit helps, and it moves faster than anything else on this list.
Do not close old cards. Length of history and mix are slow to build and easy to damage. An old card with a zero balance is an asset. Leave it open.
Do not shop off a credit app
FICO publishes many versions of your score, and mortgage lenders pull a different one than your free app shows. The number on your phone is directional, not the number you will be underwritten on. It is routinely off by enough to change your loan program.
Pull your actual reports at annualcreditreport.com — the federally authorized site, no card required. Dispute errors before a lender ever pulls you. Errors are common and they take weeks to clear.
FICO® is a registered trademark of Fair Isaac Corporation. Factor weightings are FICO’s published general model and vary somewhat by individual profile and score version.
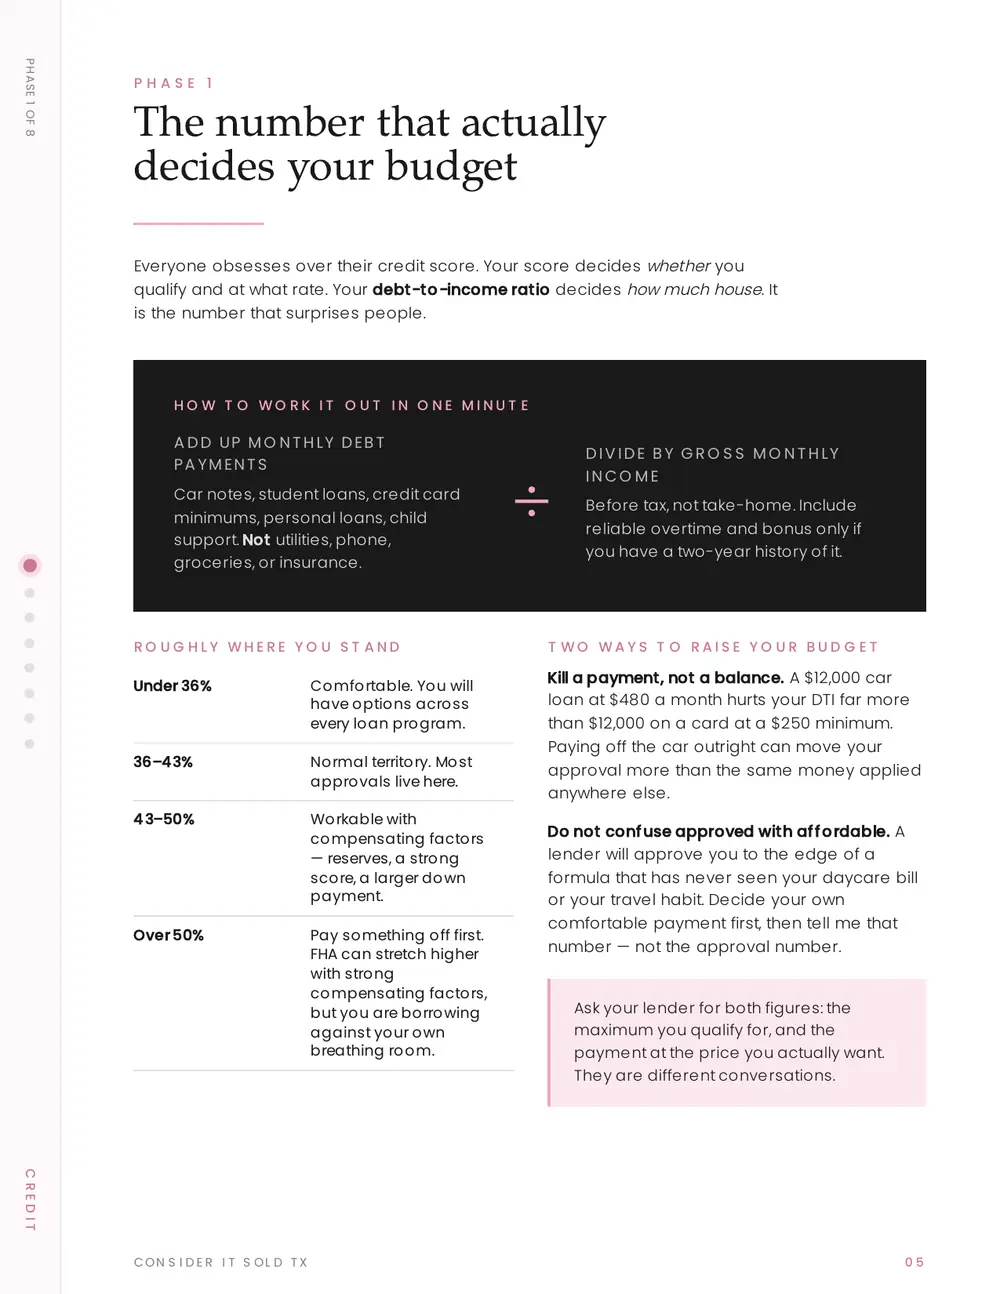
The number that actually decides your budget
Everyone obsesses over their credit score. Your debt-to-income ratio is the number that surprises people.
Add up monthly debt payments
Car notes, student loans, credit card minimums, personal loans, child support. Not utilities, phone, groceries, or insurance.
Divide by gross monthly income
Before tax, not take-home. Include reliable overtime and bonus only if you have a two-year history of it.
Roughly where you stand
- Under 36%
- Comfortable. You will have options across every loan program.
- 36–43%
- Normal territory. Most approvals live here.
- 43–50%
- Workable with compensating factors — reserves, a strong score, a larger down payment.
- Over 50%
- Pay something off first. FHA can stretch higher with strong compensating factors, but you are borrowing against your own breathing room.
Two ways to raise your budget
Kill a payment, not a balance. A $12,000 car loan at $480 a month hurts your DTI far more than $12,000 on a card at a $250 minimum. Paying off the car outright can move your approval more than the same money applied anywhere else.
Do not confuse approved with affordable. A lender will approve you to the edge of a formula that has never seen your daycare bill or your travel habit. Decide your own comfortable payment first, then tell me that number — not the approval number.
Ask your lender for both figures: the maximum you qualify for, and the payment at the price you actually want. They are different conversations.
Phase 2
The lender or the agent — which comes first?
Lenders and agents work as a team, and a good one of either will hand you a short list of the other. An experienced agent knows which lender fits your situation. A lender knows which agents negotiate well and who handles complicated files.
Call the lender first.
Not because they matter more. Because nothing else can start without them. I cannot write you an offer, and no seller in Tarrant County will look at one, without a pre-approval letter attached.
Twenty minutes and a credit pull. That is it. You are not committing to a loan, a lender, or a house.
Multiple mortgage pulls inside a short shopping window generally count as one inquiry for scoring purposes. Ask each lender to date their pull close together, and compare Loan Estimates side by side — not verbal quotes.
I keep a short list of lenders who answer their phone on a Sunday and who have closed hard files for my clients. You are free to use anyone. But if a lender will not return your call during pre-approval, imagine them three days before funding.
Phase 3
Pre-approval, the money, and which loan
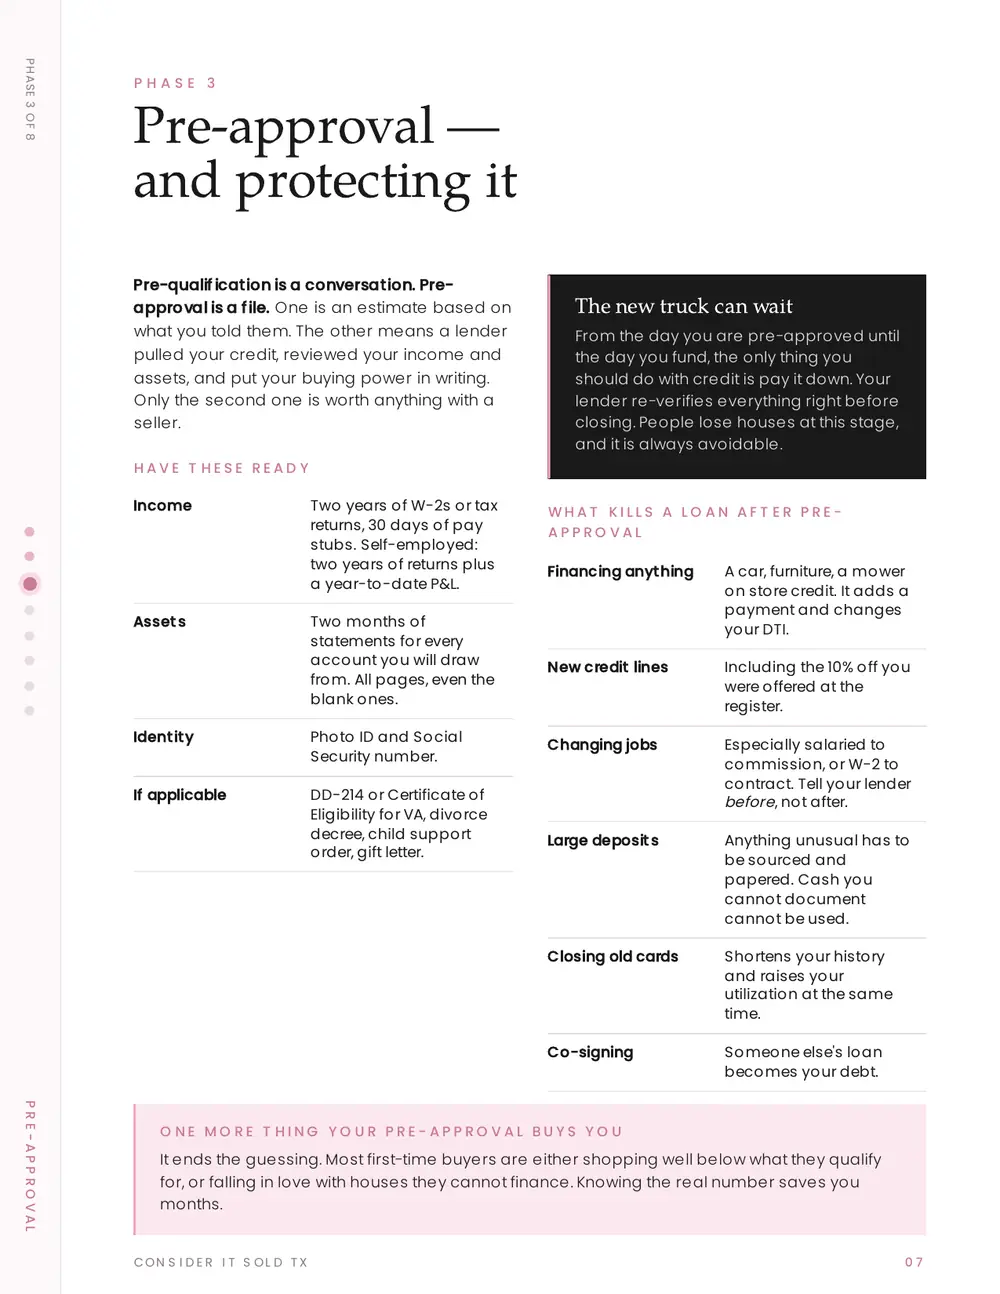
Pre-qualification is a conversation. Pre-approval is a file. Only the second one is worth anything with a seller.
One is an estimate based on what you told them. The other means a lender pulled your credit, reviewed your income and assets, and put your buying power in writing.
Have these ready
- Income
- Two years of W-2s or tax returns, 30 days of pay stubs. Self-employed: two years of returns plus a year-to-date P&L.
- Assets
- Two months of statements for every account you will draw from. All pages, even the blank ones.
- Identity
- Photo ID and Social Security number.
- If applicable
- DD-214 or Certificate of Eligibility for VA, divorce decree, child support order, gift letter.
The new truck can wait
From the day you are pre-approved until the day you fund, the only thing you should do with credit is pay it down. Your lender re-verifies everything right before closing. People lose houses at this stage, and it is always avoidable.
One more thing your pre-approval buys you
It ends the guessing. Most first-time buyers are either shopping well below what they qualify for, or falling in love with houses they cannot finance. Knowing the real number saves you months.
What kills a loan after pre-approval
- Financing anything
- A car, furniture, a mower on store credit. It adds a payment and changes your DTI.
- New credit lines
- Including the 10% off you were offered at the register.
- Changing jobs
- Especially salaried to commission, or W-2 to contract. Tell your lender before, not after.
- Large deposits
- Anything unusual has to be sourced and papered. Cash you cannot document cannot be used.
- Closing old cards
- Shortens your history and raises your utilization at the same time.
- Co-signing
- Someone else’s loan becomes your debt.
The money, and when each piece is due
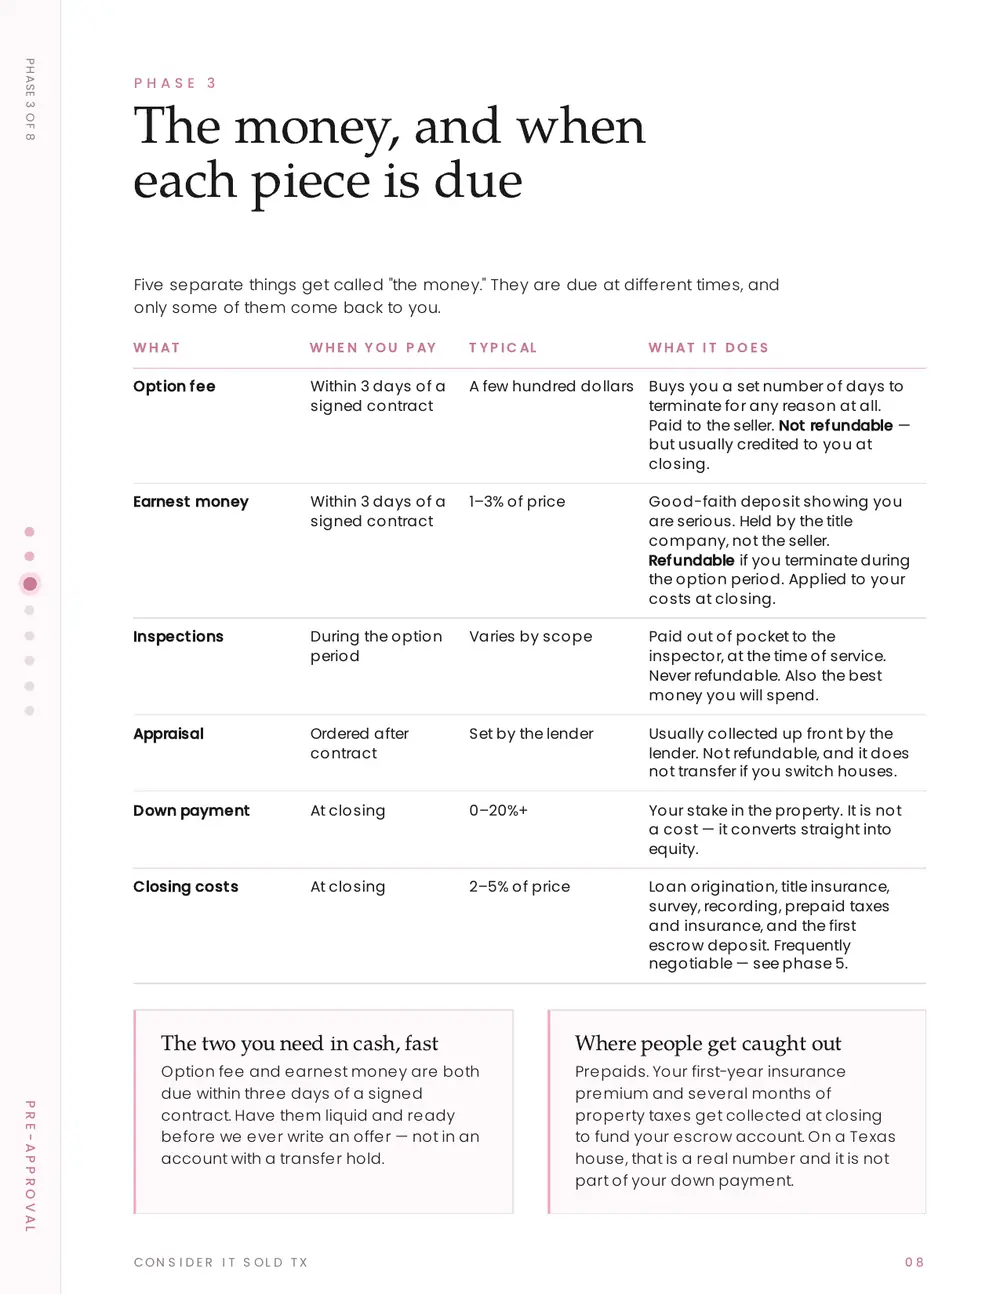
Five separate things get called “the money.” They are due at different times, and only some of them come back to you.
| What | When you pay | Typical | What it does |
|---|---|---|---|
| Option fee | Within 3 days of a signed contract | A few hundred dollars | Buys you a set number of days to terminate for any reason at all. Paid to the seller. Not refundable — but usually credited to you at closing. |
| Earnest money | Within 3 days of a signed contract | 1–3% of price | Good-faith deposit showing you are serious. Held by the title company, not the seller. Refundable if you terminate during the option period. Applied to your costs at closing. |
| Inspections | During the option period | Varies by scope | Paid out of pocket to the inspector, at the time of service. Never refundable. Also the best money you will spend. |
| Appraisal | Ordered after contract | Set by the lender | Usually collected up front by the lender. Not refundable, and it does not transfer if you switch houses. |
| Down payment | At closing | 0–20%+ | Your stake in the property. It is not a cost — it converts straight into equity. |
| Closing costs | At closing | 2–5% of price | Loan origination, title insurance, survey, recording, prepaid taxes and insurance, and the first escrow deposit. Frequently negotiable — see phase 5. |
The two you need in cash, fast
Option fee and earnest money are both due within three days of a signed contract. Have them liquid and ready before we ever write an offer — not in an account with a transfer hold.
Where people get caught out
Prepaids. Your first-year insurance premium and several months of property taxes get collected at closing to fund your escrow account. On a Texas house, that is a real number and it is not part of your down payment.
Which loan, and what it really costs
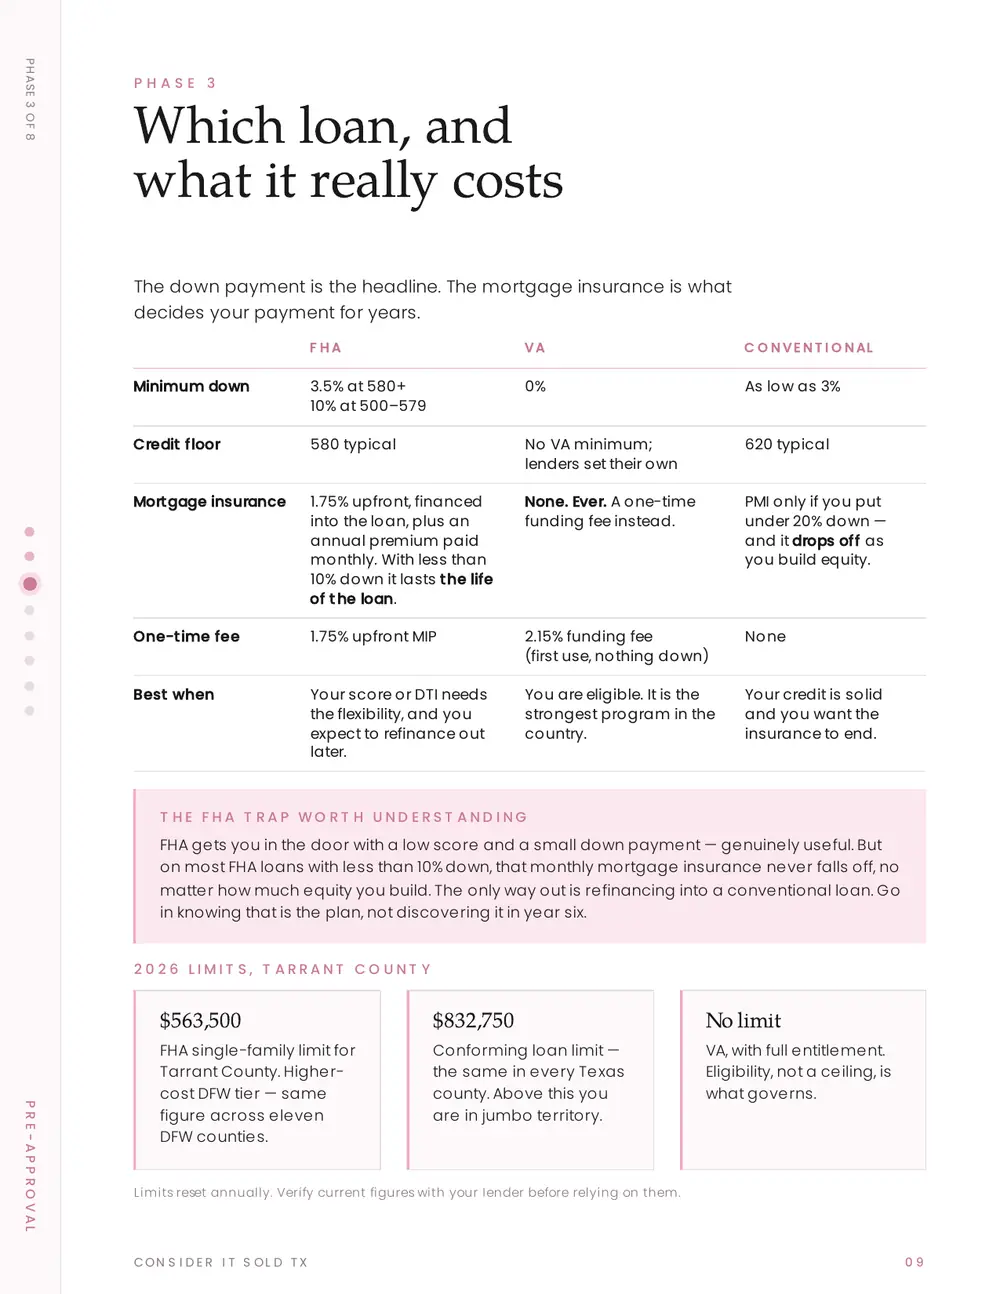
The down payment is the headline. The mortgage insurance is what decides your payment for years.
| FHA | VA | Conventional | |
|---|---|---|---|
| Minimum down | 3.5% at 580+ 10% at 500–579 | 0% | As low as 3% |
| Credit floor | 580 typical | No VA minimum; lenders set their own | 620 typical |
| Mortgage insurance | 1.75% upfront, financed into the loan, plus an annual premium paid monthly. With less than 10% down it lasts the life of the loan. | None. Ever. A one-time funding fee instead. | PMI only if you put under 20% down — and it drops off as you build equity. |
| One-time fee | 1.75% upfront MIP | 2.15% funding fee (first use, nothing down) | None |
| Best when | Your score or DTI needs the flexibility, and you expect to refinance out later. | You are eligible. It is the strongest program in the country. | Your credit is solid and you want the insurance to end. |
FHA gets you in the door with a low score and a small down payment — genuinely useful. But on most FHA loans with less than 10% down, that monthly mortgage insurance never falls off, no matter how much equity you build. The only way out is refinancing into a conventional loan. Go in knowing that is the plan, not discovering it in year six.
2026 limits, Tarrant County
$563,500
FHA single-family limit for Tarrant County. Higher-cost DFW tier — same figure across eleven DFW counties.
$832,750
Conforming loan limit — the same in every Texas county. Above this you are in jumbo territory.
No limit
VA, with full entitlement. Eligibility, not a ceiling, is what governs.
Limits reset annually. Verify current figures with your lender before relying on them.
Your VA benefit is worth more than you think
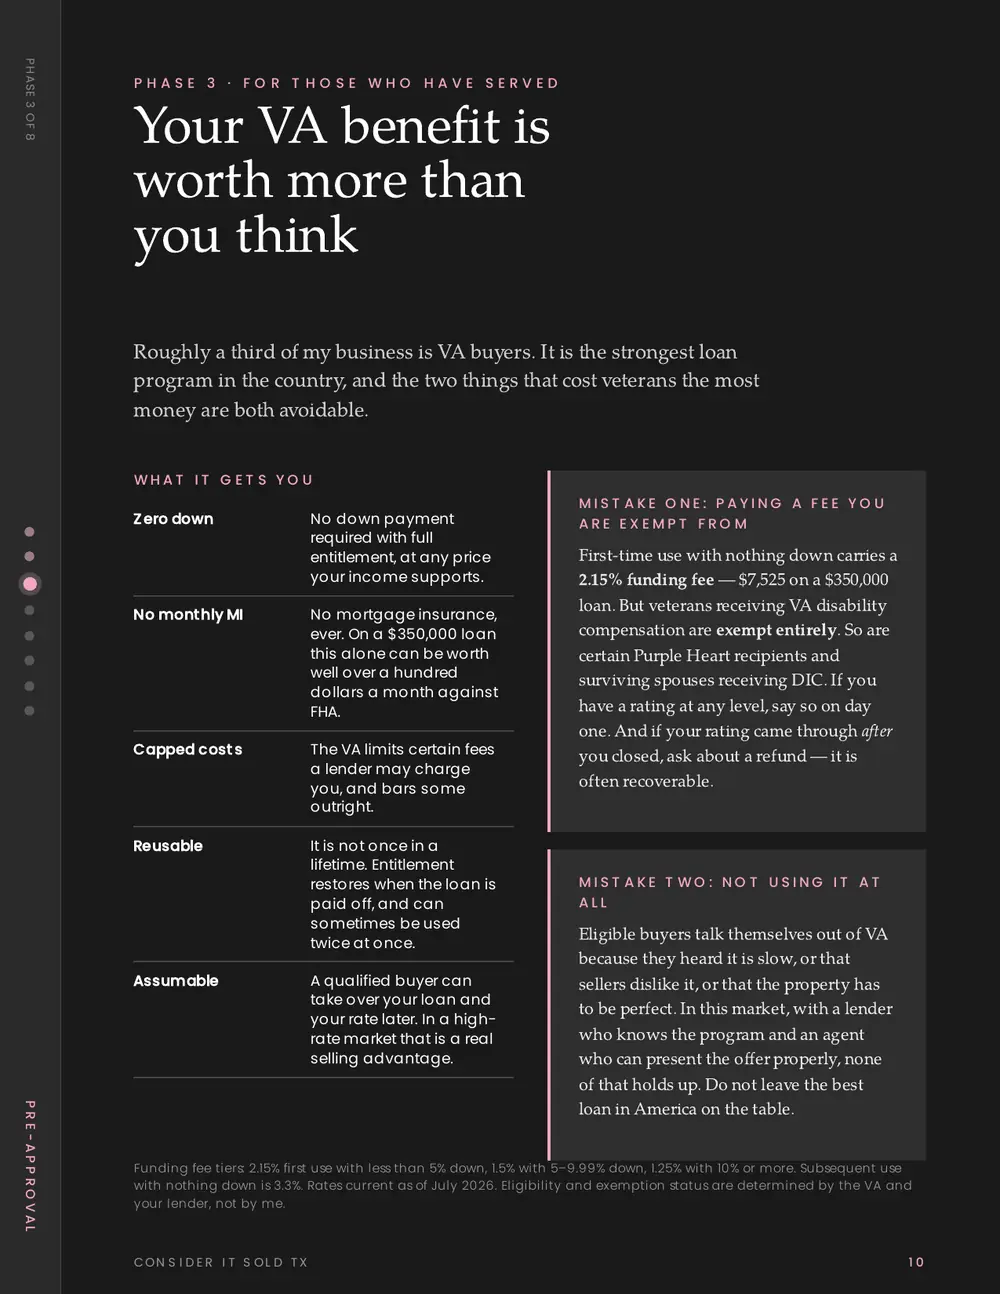
Roughly a third of my business is VA buyers. It is the strongest loan program in the country, and the two things that cost veterans the most money are both avoidable.
- Zero down
- No down payment required with full entitlement, at any price your income supports.
- No monthly MI
- No mortgage insurance, ever. On a $350,000 loan this alone can be worth well over a hundred dollars a month against FHA.
- Capped costs
- The VA limits certain fees a lender may charge you, and bars some outright.
- Reusable
- It is not once in a lifetime. Entitlement restores when the loan is paid off, and can sometimes be used twice at once.
- Assumable
- A qualified buyer can take over your loan and your rate later. In a high-rate market that is a real selling advantage.
Paying a fee you are exempt from
First-time use with nothing down carries a 2.15% funding fee — $7,525 on a $350,000 loan. But veterans receiving compensation are exempt entirely. So are certain Purple Heart recipients and surviving spouses receiving DIC. If you have a rating at any level, say so on day one. And if your rating came through after you closed, ask about a refund — it is often recoverable.
Not using it at all
Eligible buyers talk themselves out of VA because they heard it is slow, or that sellers dislike it, or that the property has to be perfect. In this market, with a lender who knows the program and an agent who can present the offer properly, none of that holds up. Do not leave the best loan in America on the table.
Funding fee tiers: 2.15% first use with less than 5% down, 1.5% with 5–9.99% down, 1.25% with 10% or more. Subsequent use with nothing down is 3.3%. Rates current as of July 2026. Eligibility and exemption status are determined by the VA and your lender, not by me.
Buying the rate down
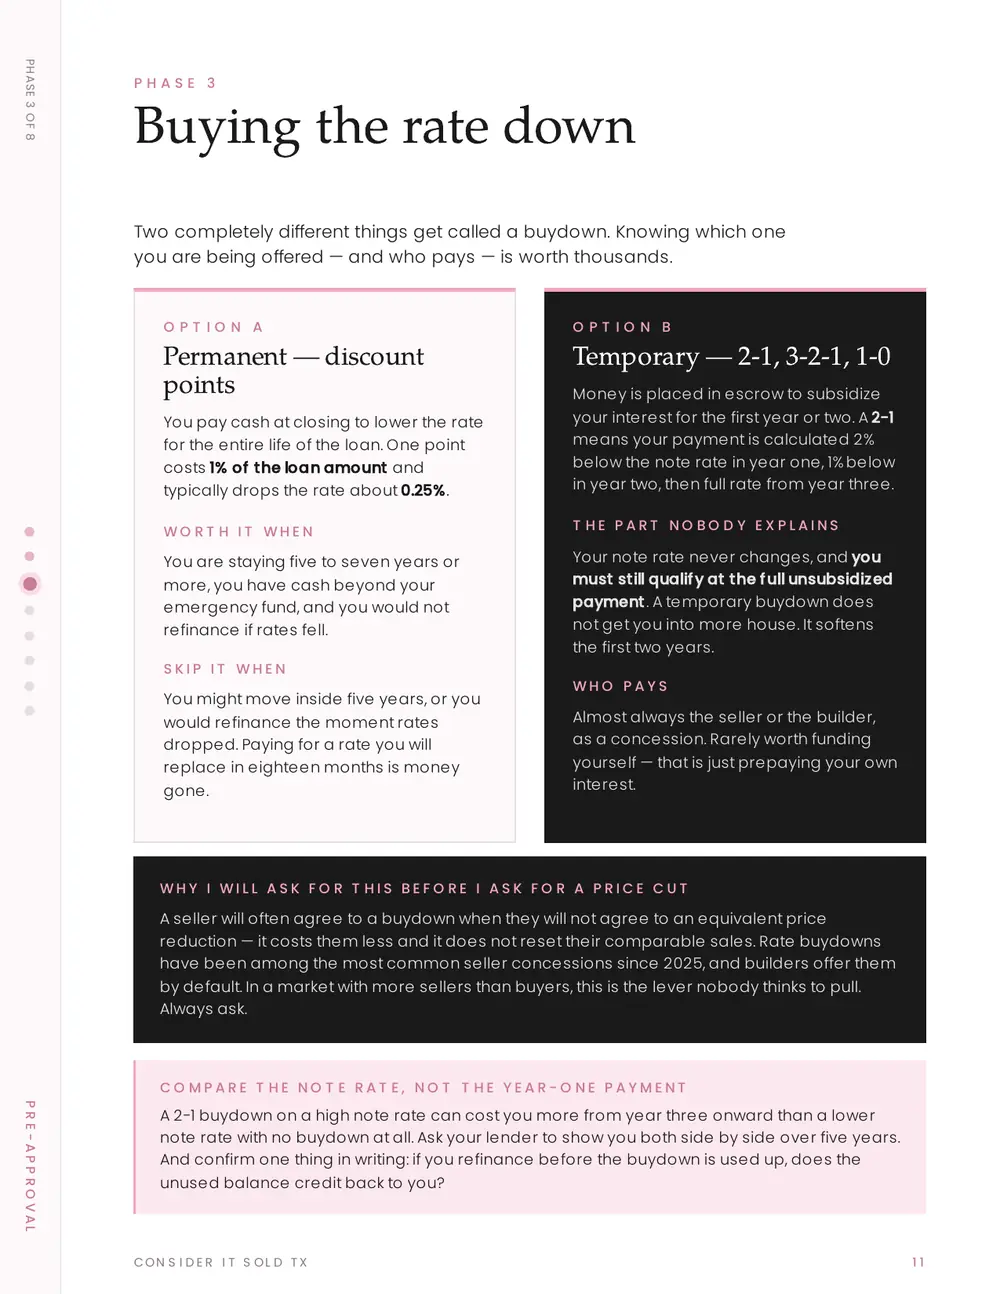
Two completely different things get called a buydown. Knowing which one you are being offered — and who pays — is worth thousands.
Permanent — discount points
You pay cash at closing to lower the rate for the entire life of the loan. One point costs 1% of the loan amount and typically drops the rate about 0.25%.
Worth it when you are staying five to seven years or more, you have cash beyond your emergency fund, and you would not refinance if rates fell.
Skip it when you might move inside five years, or you would refinance the moment rates dropped. Paying for a rate you will replace in eighteen months is money gone.
Temporary — 2-1, 3-2-1, 1-0
Money is placed in escrow to subsidize your interest for the first year or two. A 2-1 means your payment is calculated 2% below the note rate in year one, 1% below in year two, then full rate from year three.
The part nobody explains: your note rate never changes, and you must still qualify at the full unsubsidized payment. A temporary buydown does not get you into more house. It softens the first two years.
Who pays: almost always the seller or the builder, as a concession. Rarely worth funding yourself — that is just prepaying your own interest.
A seller will often agree to a buydown when they will not agree to an equivalent price reduction — it costs them less and it does not reset their comparable sales. Rate buydowns have been among the most common seller concessions since 2025, and builders offer them by default. In a market with more sellers than buyers, this is the lever nobody thinks to pull. Always ask.
A 2-1 buydown on a high note rate can cost you more from year three onward than a lower note rate with no buydown at all. Ask your lender to show you both side by side over five years. And confirm one thing in writing: if you refinance before the buydown is used up, does the unused balance credit back to you?
Phase 4
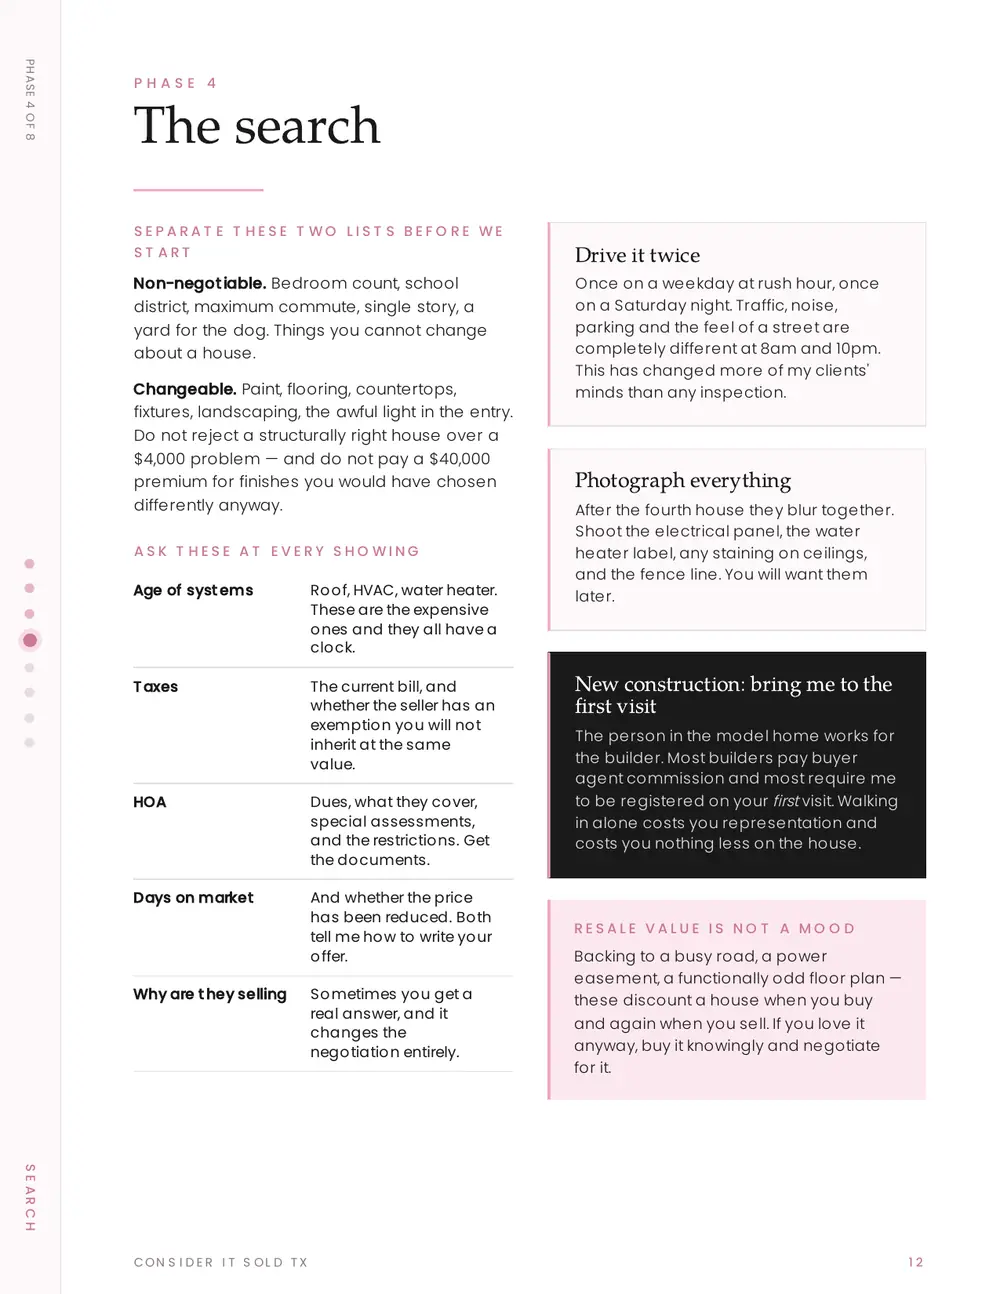
The search
Now the fun part. Before we start, two lists — and they are not the same list.
Non-negotiable. Bedroom count, school district, maximum commute, single story, a yard for the dog. Things you cannot change about a house.
Changeable. Paint, flooring, countertops, fixtures, landscaping, the awful light in the entry. Do not reject a structurally right house over a $4,000 problem — and do not pay a $40,000 premium for finishes you would have chosen differently anyway.
Drive it twice
Once on a weekday at rush hour, once on a Saturday night. Traffic, noise, parking and the feel of a street are completely different at 8am and 10pm. This has changed more of my clients’ minds than any inspection.
Ask these at every showing
- Age of systems
- Roof, HVAC, water heater. These are the expensive ones and they all have a clock.
- Taxes
- The current bill, and whether the seller has an exemption you will not inherit at the same value.
- HOA
- Dues, what they cover, special assessments, and the restrictions. Get the documents.
- Days on market
- And whether the price has been reduced. Both tell me how to write your offer.
- Why are they selling
- Sometimes you get a real answer, and it changes the negotiation entirely.
New construction: bring me to the first visit
The person in the model home works for the builder. Most builders pay buyer agent commission and most require me to be registered on your first visit. Walking in alone costs you representation and costs you nothing less on the house.
Photograph everything
After the fourth house they blur together. Shoot the electrical panel, the water heater label, any staining on ceilings, and the fence line. You will want them later.
Backing to a busy road, a power easement, a functionally odd floor plan — these discount a house when you buy and again when you sell. If you love it anyway, buy it knowingly and negotiate for it.
Rate every home you tour on the same seven categories so they stop blurring together.
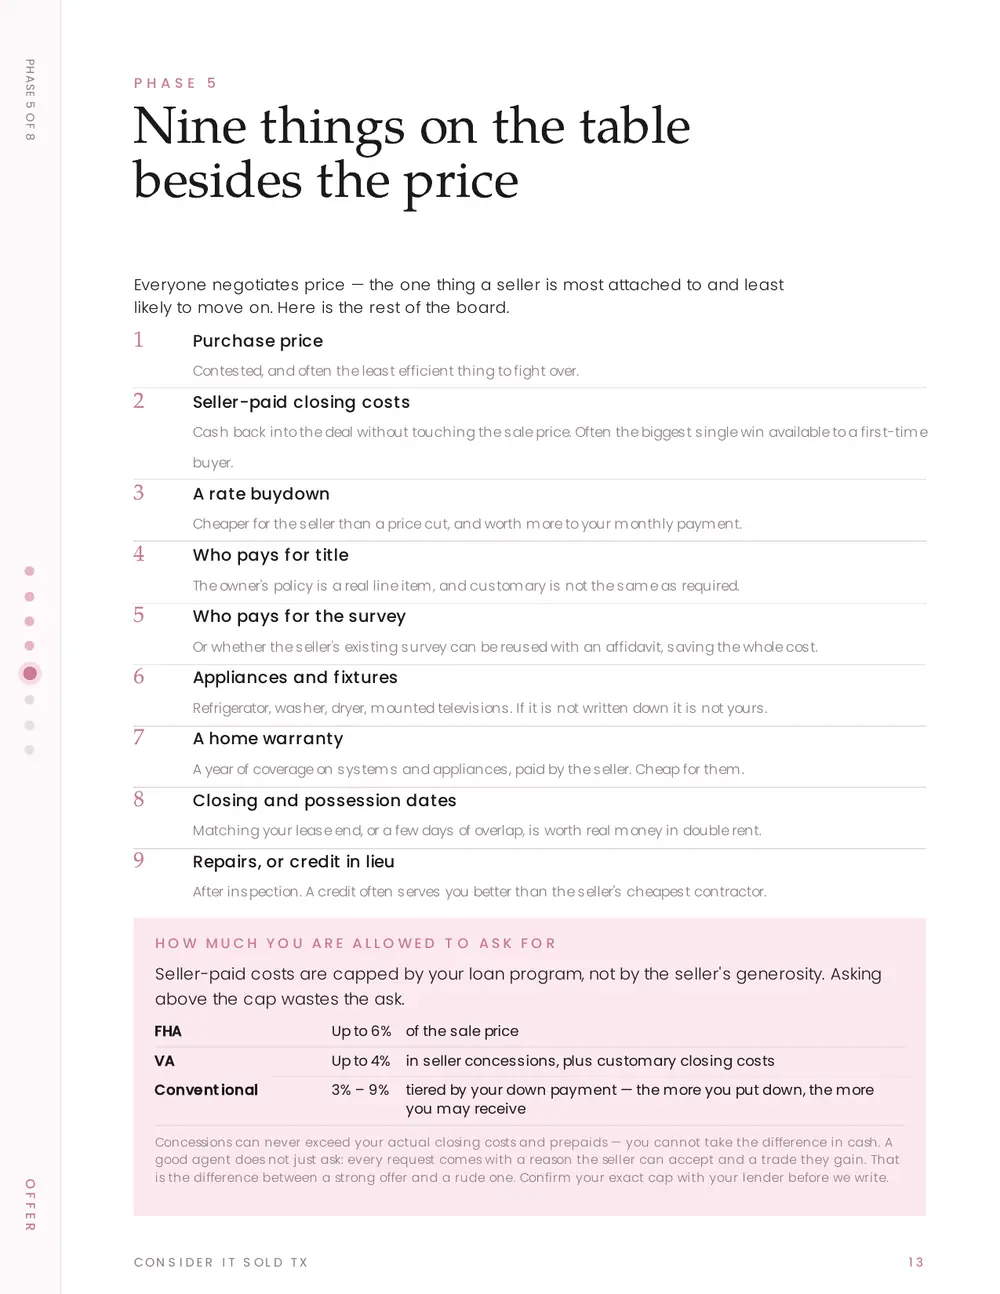
Phase 5
Nine things on the table besides the price
Everyone negotiates price — the one thing a seller is most attached to and least likely to move on. Here is the rest of the board.
- Purchase priceContested, and often the least efficient thing to fight over.
- Seller-paid closing costsCash back into the deal without touching the sale price. Often the biggest single win available to a first-time buyer.
- A rate buydownCheaper for the seller than a price cut, and worth more to your monthly payment.
- Who pays for titleThe owner’s policy is a real line item, and customary is not the same as required.
- Who pays for the surveyOr whether the seller’s existing survey can be reused with an affidavit, saving the whole cost.
- Appliances and fixturesRefrigerator, washer, dryer, mounted televisions. If it is not written down it is not yours.
- A home warrantyA year of coverage on systems and appliances, paid by the seller. Cheap for them.
- Closing and possession datesMatching your lease end, or a few days of overlap, is worth real money in double rent.
- Repairs, or credit in lieuAfter inspection. A credit often serves you better than the seller’s cheapest contractor.
How much you are allowed to ask for
Seller-paid costs are capped by your loan program, not by the seller’s generosity. Asking above the cap wastes the ask.
| Program | Cap | Notes |
|---|---|---|
| FHA | Up to 6% | of the sale price |
| VA | Up to 4% | in seller concessions, plus customary closing costs |
| Conventional | 3% – 9% | tiered by your down payment — the more you put down, the more you may receive |
Concessions can never exceed your actual closing costs and prepaids — you cannot take the difference in cash. A good agent does not just ask: every request comes with a reason the seller can accept and a trade they gain. That is the difference between a strong offer and a rude one. Confirm your exact cap with your lender before we write.
Phase 6
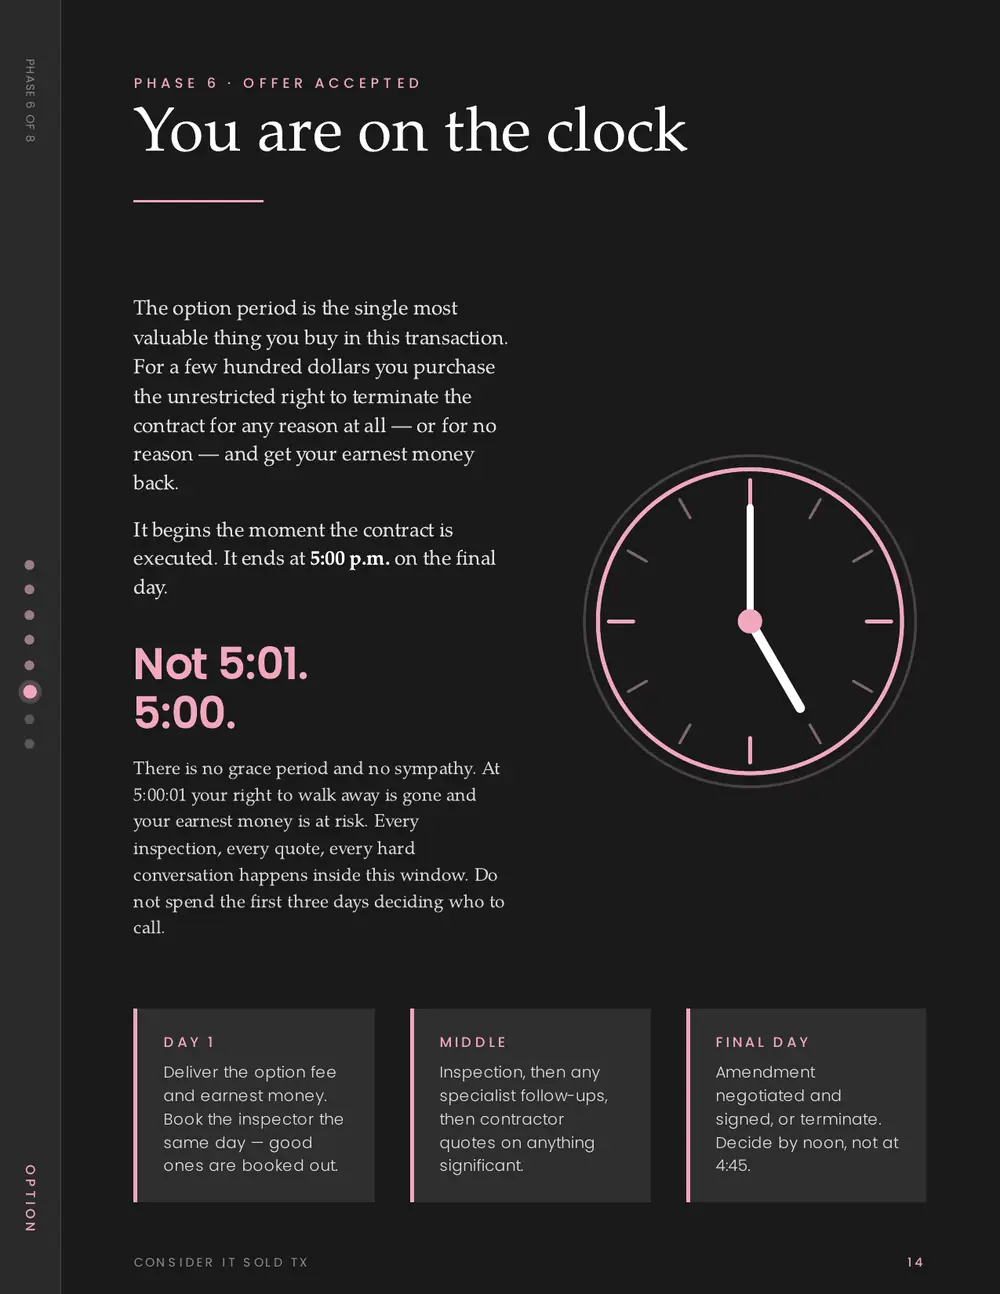
The option period
The option period is the single most valuable thing you buy in this transaction. For a few hundred dollars you purchase the unrestricted right to terminate the contract for any reason at all — or for no reason — and get your earnest money back.
It begins the moment the contract is executed. It ends at 5:00 p.m. on the final day.
Not 5:01. 5:00.
There is no grace period and no sympathy. At 5:00:01 your right to walk away is gone and your earnest money is at risk. Every inspection, every quote, every hard conversation happens inside this window. Do not spend the first three days deciding who to call.
Deliver the option fee and earnest money. Book the inspector the same day — good ones are booked out.
Inspection, then any specialist follow-ups, then contractor quotes on anything significant.
Amendment negotiated and signed, or terminate. Decide by noon, not at 4:45.
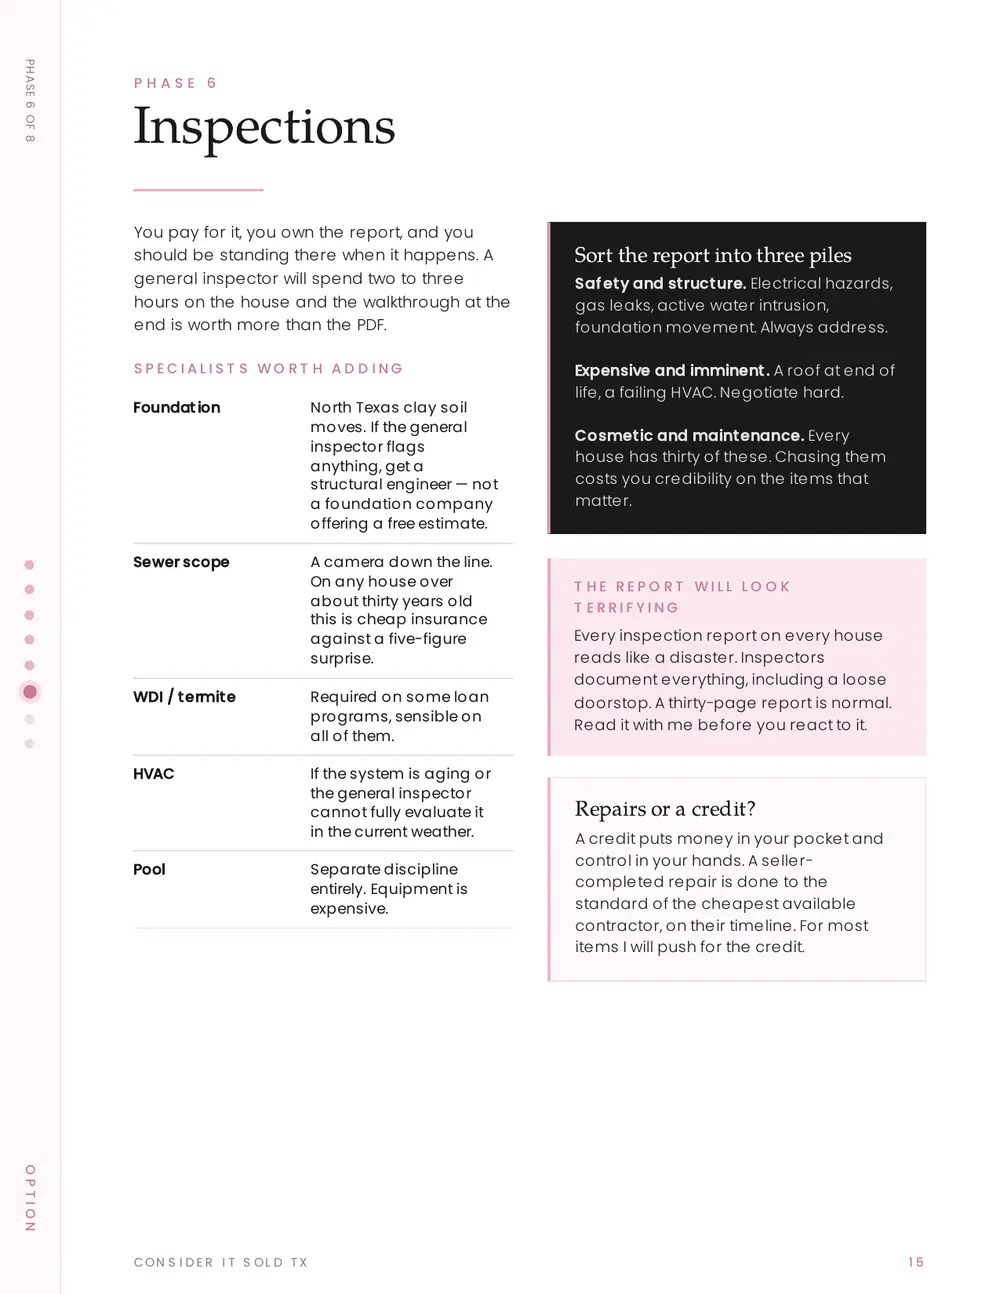
Inspections
You pay for it, you own the report, and you should be standing there when it happens. A general inspector will spend two to three hours on the house and the walkthrough at the end is worth more than the PDF.
Specialists worth adding
- Foundation
- North Texas clay soil moves. If the general inspector flags anything, get a structural engineer — not a foundation company offering a free estimate.
- Sewer scope
- A camera down the line. On any house over about thirty years old this is cheap insurance against a five-figure surprise.
- WDI / termite
- Required on some loan programs, sensible on all of them.
- HVAC
- If the system is aging or the general inspector cannot fully evaluate it in the current weather.
- Pool
- Separate discipline entirely. Equipment is expensive.
Sort the report into three piles
Safety and structure. Electrical hazards, gas leaks, active water intrusion, foundation movement. Always address.
Expensive and imminent. Roof at end of life, a failing HVAC. Negotiate hard.
Cosmetic and maintenance. Every house has thirty of these. Chasing them costs you credibility on the items that matter.
The report will look terrifying
Every inspection report on every house reads like a disaster. Inspectors document everything, including a loose doorstop. A thirty-page report is normal. Read it with me before you react to it.
Repairs or a credit?
A credit puts money in your pocket and control in your hands. A seller-completed repair is done to the standard of the cheapest available contractor, on their timeline. For most items I will push for the credit.
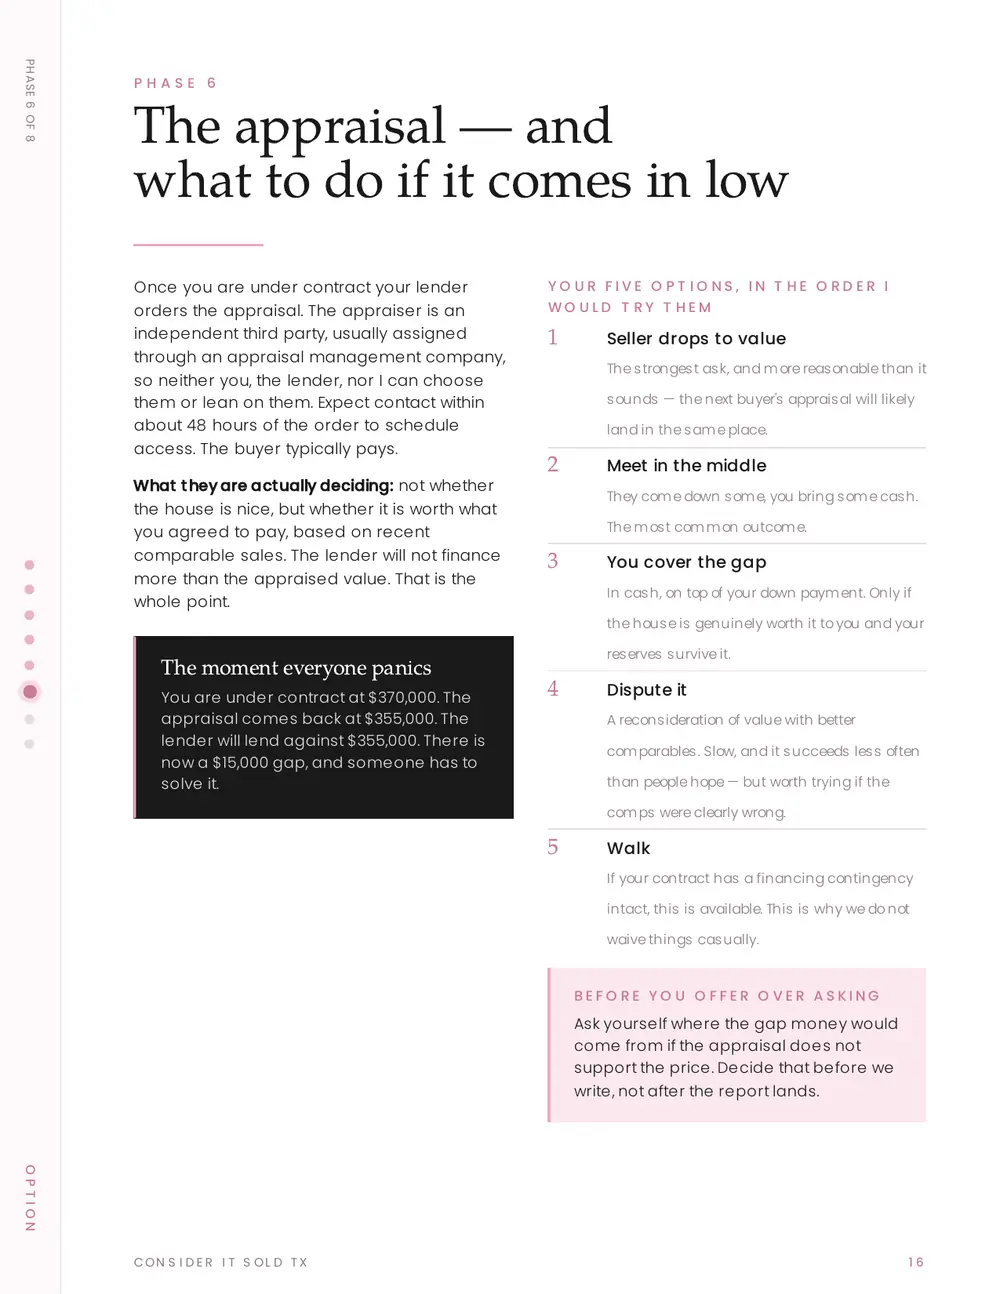
The appraisal — and what to do if it comes in low
Once you are under contract your lender orders the appraisal. The appraiser is an independent third party, usually assigned through an appraisal management company, so neither you, the lender, nor I can choose them or lean on them. Expect contact within about 48 hours of the order to schedule access. The buyer typically pays.
What they are actually deciding: not whether the house is nice, but whether it is worth what you agreed to pay, based on recent comparable sales. The lender will not finance more than the appraised value. That is the whole point.
You are under contract at $370,000. The appraisal comes back at $355,000. The lender will lend against $355,000. There is now a $15,000 gap, and someone has to solve it.
Your five options, in the order I would try them
- Seller drops to valueThe strongest ask, and more reasonable than it sounds — the next buyer’s appraisal will likely land in the same place.
- Meet in the middleThey come down some, you bring some cash. The most common outcome.
- You cover the gapIn cash, on top of your down payment. Only if the house is genuinely worth it to you and your reserves survive it.
- Dispute itA reconsideration of value with better comparables. Slow, and it succeeds less often than people hope — but worth trying if the comps were clearly wrong.
- WalkIf your contract has a financing contingency intact, this is available. This is why we do not waive things casually.
Ask yourself where the gap money would come from if the appraisal does not support the price. Decide that before we write, not after the report lands.
Phase 7
Closing day and the first year
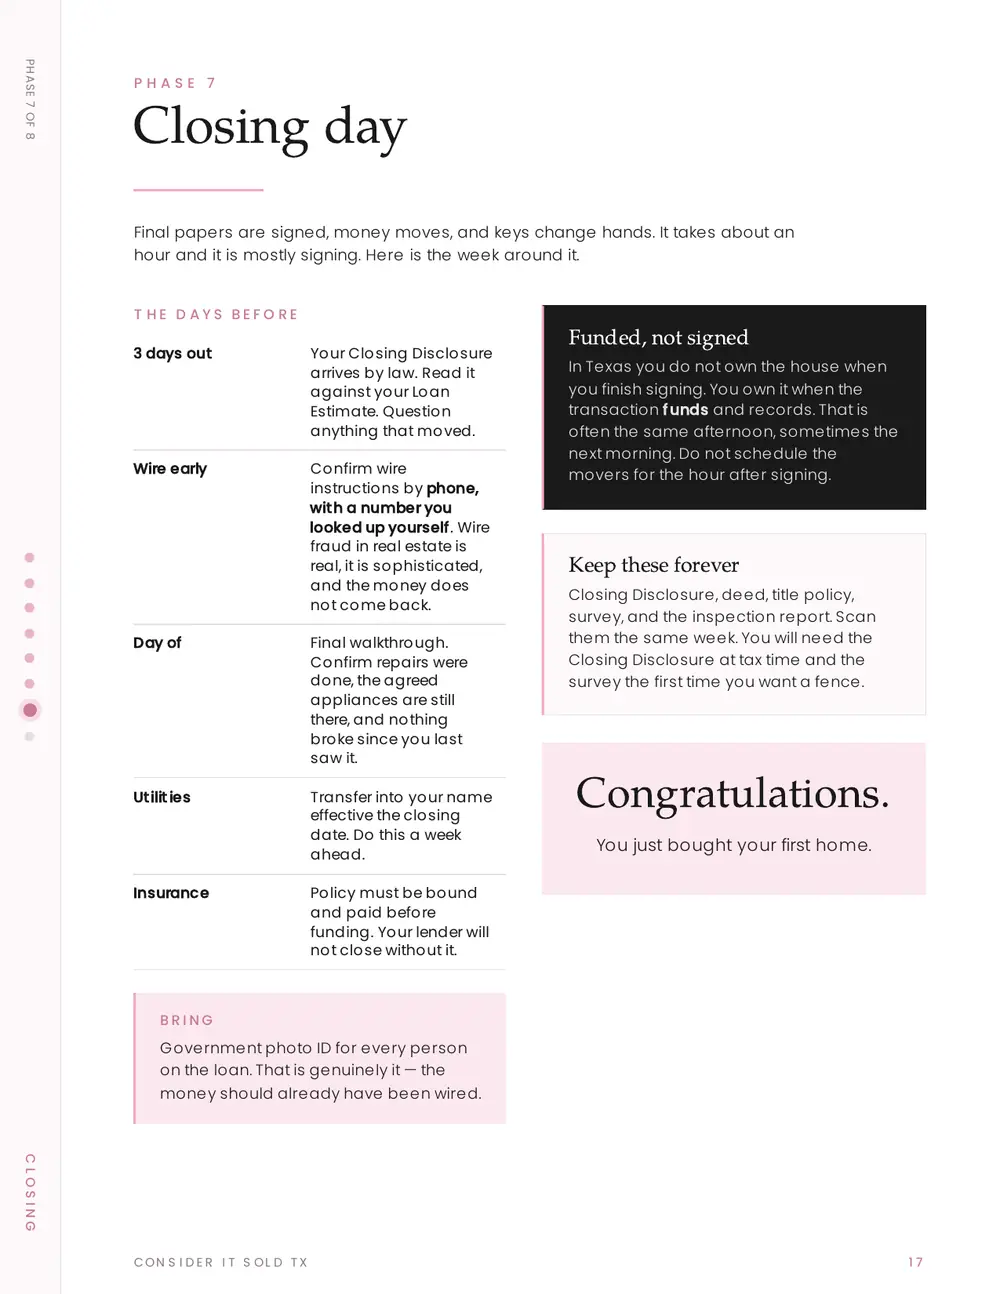
Final papers are signed, money moves, and keys change hands. It takes about an hour and it is mostly signing. Here is the week around it.
The days before
- 3 days out
- Your Closing Disclosure arrives by law. Read it against your Loan Estimate. Question anything that moved.
- Wire early
- Confirm wire instructions by phone, with a number you looked up yourself. Wire fraud in real estate is real, it is sophisticated, and the money does not come back.
- Day of
- Final walkthrough. Confirm repairs were done, the agreed appliances are still there, and nothing broke since you last saw it.
- Utilities
- Transfer into your name effective the closing date. Do this a week ahead.
- Insurance
- Policy must be bound and paid before funding. Your lender will not close without it.
Funded, not signed
In Texas you do not own the house when you finish signing. You own it when the transaction funds and records. That is often the same afternoon, sometimes the next morning. Do not schedule the movers for the hour after signing.
Keep these forever
Closing Disclosure, deed, title policy, survey, and the inspection report. Scan them. You will need the Closing Disclosure at tax time and the survey the first time you want a fence.
Government photo ID for every person on the loan. That is genuinely it — the money should already have been wired.
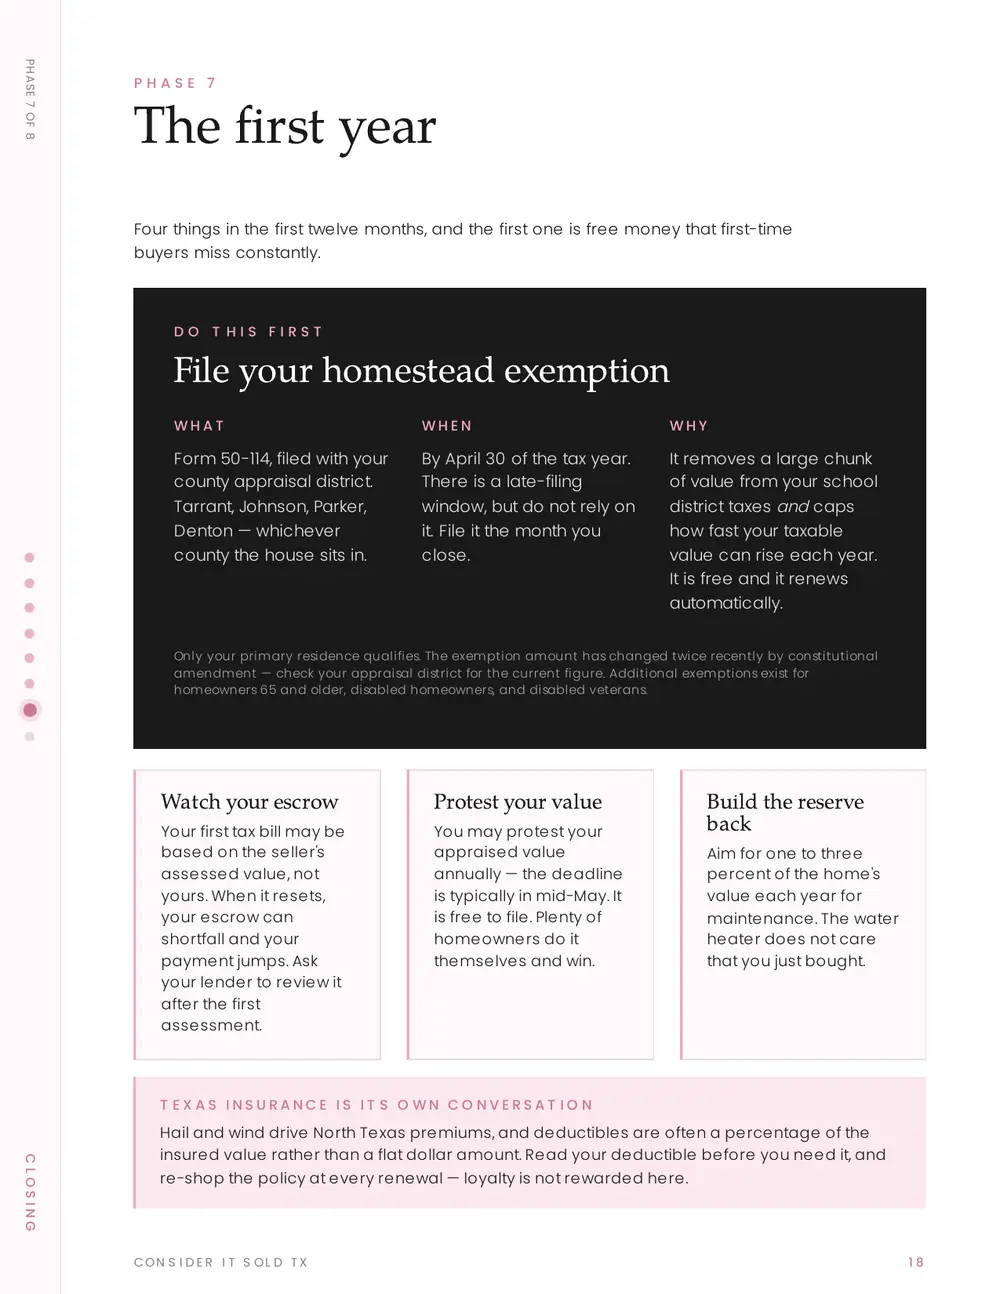
The first year
Four things in the first twelve months, and the first one is free money that first-time buyers miss constantly.
File your homestead exemption
What: Form 50-114, filed with your county appraisal district. Tarrant, Johnson, Parker, Denton — whichever county the house sits in.
When: By April 30 of the tax year. There is a late-filing window, but do not rely on it. File it the month you close.
Why: It removes a large chunk of value from your school district taxes and caps how fast your taxable value can rise each year. It is free and it renews automatically.
Only your primary residence qualifies. The exemption amount has changed twice recently by constitutional amendment — check your appraisal district for the current figure. Additional exemptions exist for homeowners 65 and older, disabled homeowners, and disabled veterans.
Watch your escrow
Your first tax bill may be based on the seller’s assessed value, not yours. When it resets, your escrow can shortfall and your payment jumps. Ask your lender to review it after the first assessment.
Protest your value
You may protest your appraised value annually — the deadline is typically mid-May. It is free to file. Plenty of homeowners do it themselves and win.
Build the reserve back
Aim for one to three percent of the home’s value each year for maintenance. The water heater does not care that you just bought.
Hail and wind drive North Texas premiums, and deductibles are often a percentage of the insured value rather than a flat dollar amount. Read your deductible before you need it, and re-shop the policy at every renewal — loyalty is not rewarded here.
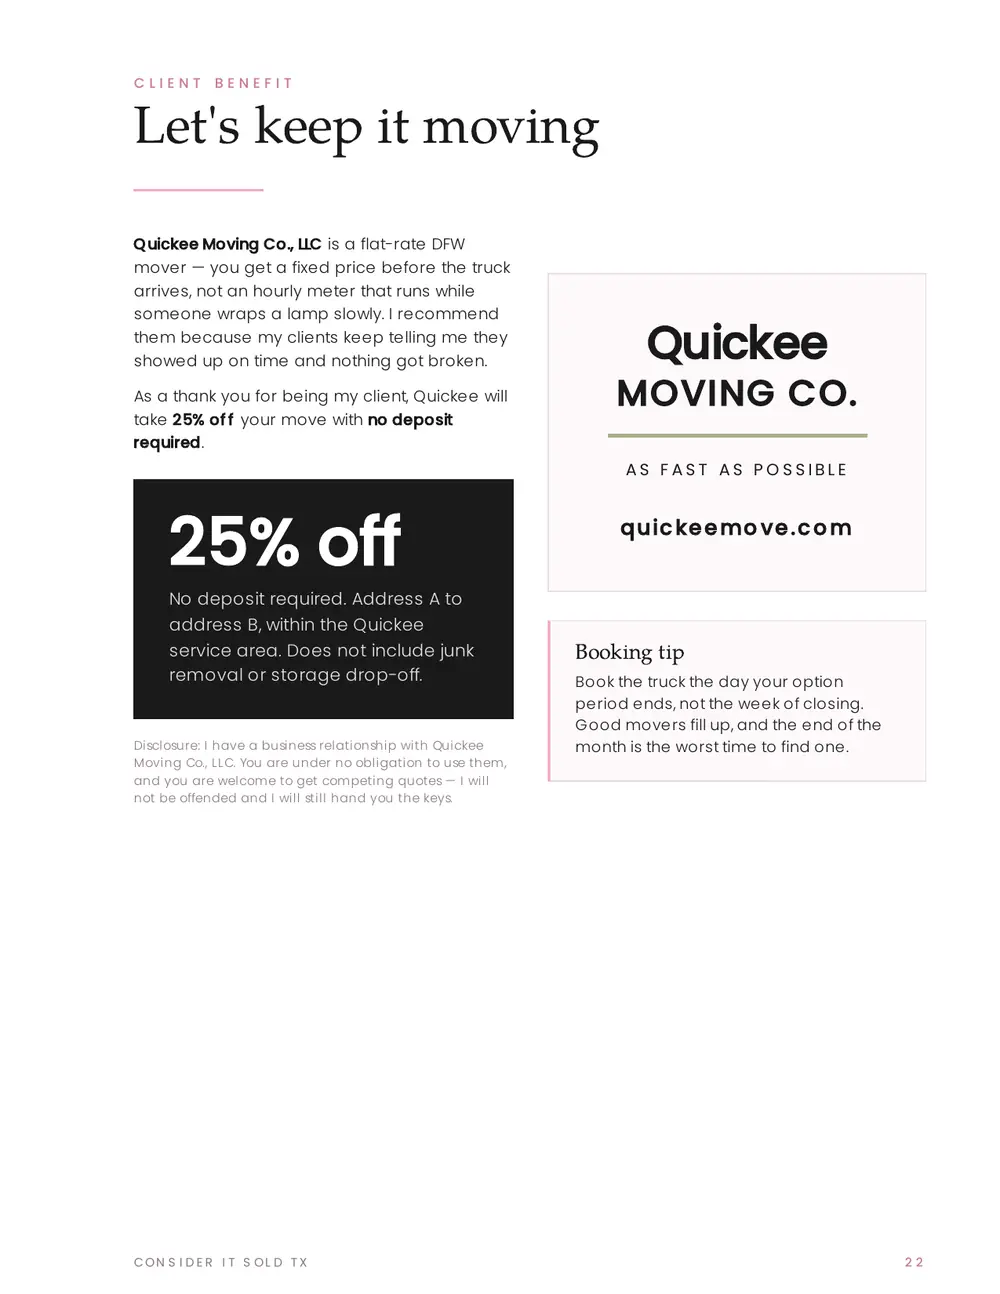
Let’s keep it moving
Quickee Moving Co., LLC is a flat-rate DFW mover — you get a fixed price before the truck arrives, not an hourly meter that runs while someone wraps a lamp slowly. I recommend them because my clients keep telling me they showed up on time and nothing got broken.
As a thank you for being my client, Quickee will take 25% off your move with no deposit required.
25% off
No deposit required. Address A to address B, within the Quickee service area. Does not include junk removal or storage drop-off.
Book the truck the day your option period ends, not the week of closing. Good movers fill up, and the end of the month is the worst time to find one.
Disclosure: I have a business relationship with Quickee Moving Co., LLC. You are under no obligation to use them, and you are welcome to get competing quotes — I will not be offended and I will still hand you the keys.
Phase 8
Putting equity to work
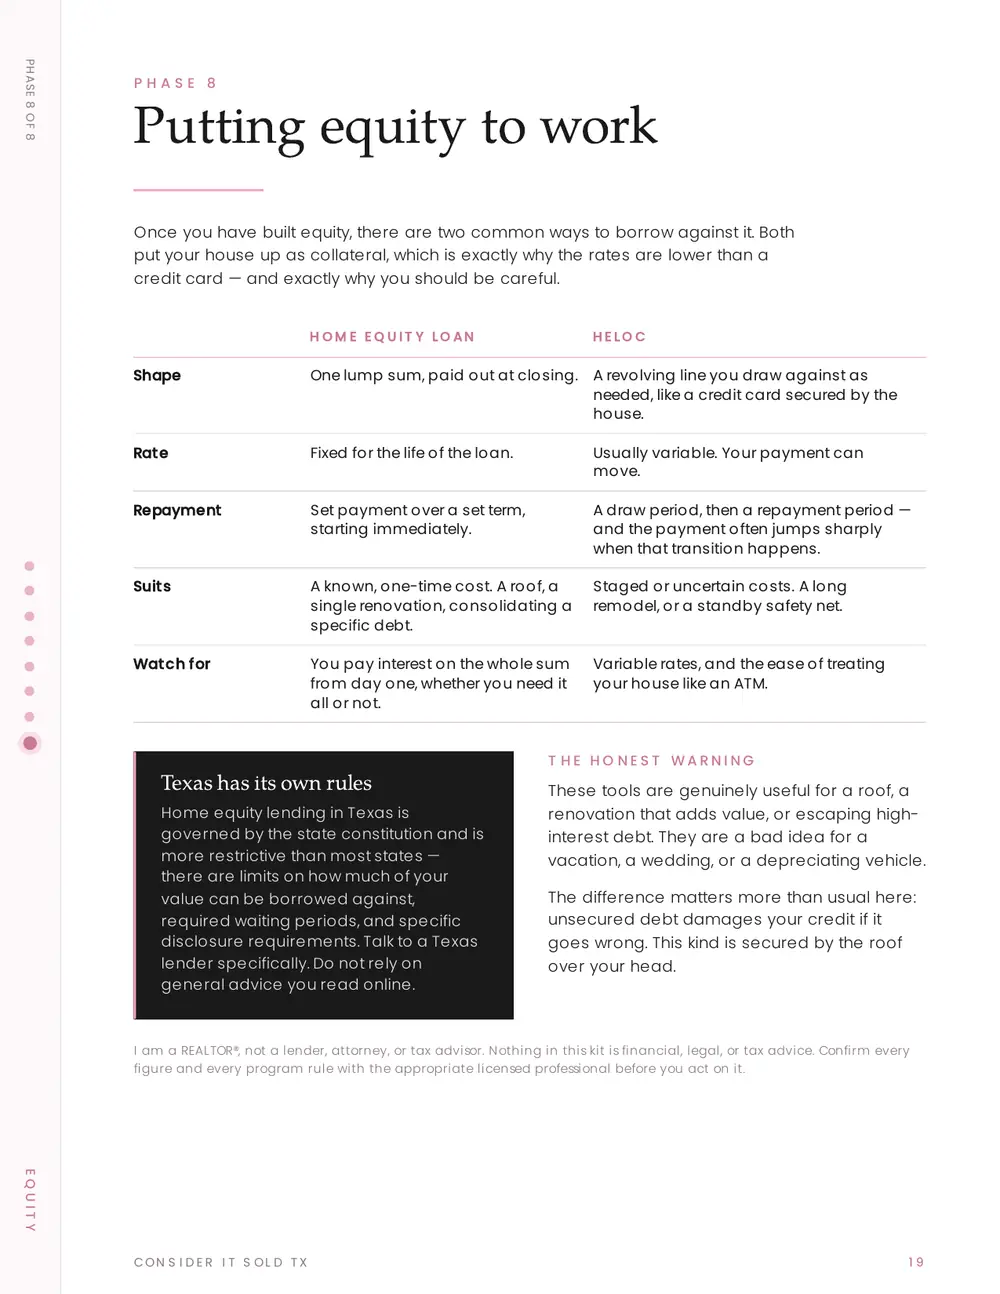
Once you have built equity, there are two common ways to borrow against it. Both put your house up as collateral, which is exactly why the rates are lower than a credit card — and exactly why you should be careful.
| Home equity loan | HELOC | |
|---|---|---|
| Shape | One lump sum, paid out at closing. | A revolving line you draw against as needed, like a credit card secured by the house. |
| Rate | Fixed for the life of the loan. | Usually variable. Your payment can move. |
| Repayment | Set payment over a set term, starting immediately. | A draw period, then a repayment period — and the payment often jumps sharply when that transition happens. |
| Suits | A known, one-time cost. A roof, a single renovation, consolidating a specific debt. | Staged or uncertain costs. A long remodel, or a standby safety net. |
| Watch for | You pay interest on the whole sum from day one, whether you need it all or not. | Variable rates, and the ease of treating your house like an ATM. |
Texas has its own rules
Home equity lending in Texas is governed by the state constitution and is more restrictive than most states — there are limits on how much of your value can be borrowed against, required waiting periods, and specific disclosure requirements. Talk to a Texas lender specifically. Do not rely on general advice you read online.
These tools are genuinely useful for a roof, a renovation that adds value, or escaping high-interest debt. They are a bad idea for a vacation, a wedding, or a depreciating vehicle.
The difference matters more than usual here: unsecured debt damages your credit if it goes wrong. This kind is secured by the roof over your head.
I am a REALTOR®, not a lender, attorney, or tax advisor. Nothing in this guide is financial, legal, or tax advice. Program rules, limits, and rates change — confirm every figure with your lender, title company, or attorney before you act on it. Each office independently owned and operated. Equal Housing Opportunity.